
Categories
Homebuyer Updates, Market InsightsPublished September 14, 2026
Mortgage Rates Are Above 7%: Why Buyers Still Have Leverage in 2026

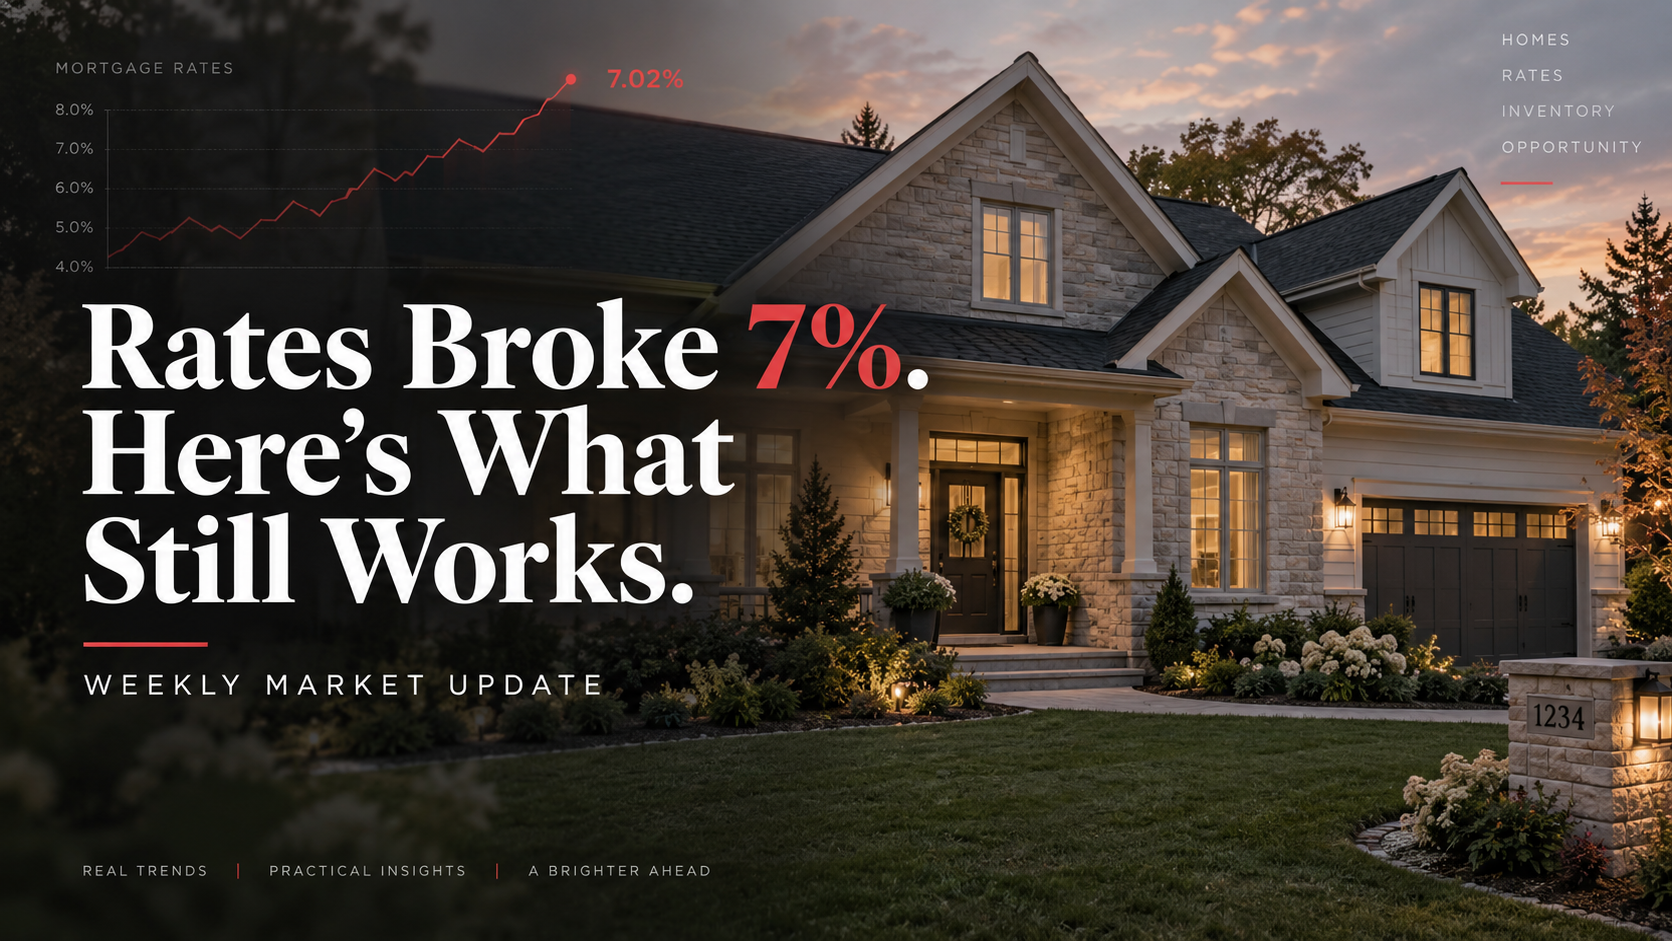
Mortgage Rates Are Back Above 7% — But Buyers May Have More Leverage Than They Think
Mortgage rates moved back above 7% this week, and for buyers already watching monthly payments closely, that headline can feel discouraging.
But a higher mortgage rate does not automatically mean it is a bad time to buy a home.
In fact, some of the other numbers moving through the housing market right now may be creating opportunities buyers have not had during more competitive markets.
The key is to stop looking at the interest rate by itself.
What Happened to Mortgage Rates?
The average 30-year fixed mortgage rate climbed to approximately 7.1% last week, moving above 7% for the first time in more than a year, according to the September 14 Market Spotlight data.
The report attributes much of the increase to rising oil prices and geopolitical concerns surrounding the Iran conflict, which pushed bond yields higher. Inflation data itself did not deliver a major new surprise.
That distinction matters.
This was not necessarily a sudden change in the underlying housing market. It was largely a reaction within the broader financial markets.
And rates may remain volatile.
The Federal Reserve is scheduled to announce its next rate decision on Wednesday, September 16, which could create additional movement as financial markets interpret what the Fed says about the path ahead.
But Buyer Demand Is Also Cooling
Higher rates tend to affect affordability, and some potential buyers respond by stepping out of the market.
We are seeing evidence of that now.
Nationally, weekly pending home sales fell to 56,255, down about 12.7% from the previous week and 9.5% from the same period last year.
Mortgage application activity also remains below last year's level.
For someone actively trying to purchase a home, fewer competing buyers can change the entire negotiation.
Instead of asking only:
“What mortgage rate can I get?”
buyers should also be asking:
“What can I negotiate on the house?”
Because the second question can sometimes have just as much impact on the overall cost of homeownership.
Inventory Is Still Higher Than Last Year
National housing inventory dipped slightly this week to approximately 873,978 homes, but inventory remained about 1.6% higher than a year ago.
New listings also declined during the week, although the Market Spotlight notes that the decrease is consistent with the normal seasonal pullback rather than evidence of a major shift in supply.
That leaves an important dynamic in place:
Demand has softened more than supply.
For buyers, that can mean:
- More homes to consider
- Fewer multiple-offer situations in some price ranges
- More time to evaluate a property
- Greater potential to negotiate price or terms
- More opportunity to request seller concessions
Of course, real estate remains highly local. Conditions in Lake of the Ozarks, Jefferson City, Columbia, and the Fort Leonard Wood/Waynesville–St. Robert area can vary considerably by neighborhood, property type, and price point.
That is why national headlines should be the beginning of the conversation — not the entire decision.
More Than 42% of Listings Have Seen a Price Reduction
Another number worth watching is the percentage of properties experiencing price reductions.
The latest national data puts that figure at approximately 42.1%.
That does not mean every seller will negotiate aggressively.
It does tell us that pricing matters.
Homes that entered the market above what buyers are willing to pay are increasingly being adjusted. For buyers who are prepared, pre-approved, and working with an agent who understands the local market, those adjustments can create opportunities.
A seller may be willing to discuss more than simply the purchase price.
Depending on the property and transaction, negotiations could involve closing-cost assistance, repairs, possession terms or other concessions.
The Interest Rate Is Only One Part of the Equation
It is easy to look at a 7% rate and immediately compare it with the much lower mortgage rates available several years ago.
But buyers cannot purchase yesterday's mortgage rate.
They can only evaluate today's combination of price, payment, inventory and negotiating power.
And those variables do not always move in the same direction.
When mortgage rates fall significantly, buyer demand can increase quickly. More buyers competing for the same homes can eventually reduce some of the negotiating leverage available today.
That does not mean buyers should rush into a purchase because rates might change.
It means waiting for a “perfect” mortgage rate is not the only strategy worth considering.
The better question is:
Does the complete financial picture work for you today?
That includes the purchase price, monthly payment, taxes, insurance, loan structure, available cash, expected length of ownership and the terms you may be able to negotiate.
Could a Temporary Mortgage Buydown Help?
The Market Spotlight also highlights a 1/0 temporary mortgage rate buydown, which reduces the borrower's interest rate by one percentage point during the first year.
Certain lenders may offer lender-paid versions of these programs, subject to borrower qualification and individual program requirements.
For example, rather than looking only at a headline rate above 7%, a qualified buyer may be able to explore financing structures that reduce the initial payment.
Buydowns are not the right solution for everyone, and buyers should review the actual long-term payment and program terms with a qualified mortgage professional.
But they are another reason buyers should run the numbers instead of making a decision based solely on a headline.
What This Means for Missouri Homebuyers
If you are considering buying around Lake of the Ozarks, Jefferson City, Columbia, Fort Leonard Wood, Waynesville, St. Robert or the surrounding Mid-Missouri communities, this is a market where preparation matters.
Rather than trying to predict the exact week mortgage rates will fall, start with the information you can know now:
What homes are available?
How long have they been on the market?
Have they already had a price adjustment?
How much competition is there in your price range?
What might the seller be willing to negotiate?
What would your actual payment look like with today's financing options?
Those answers can tell you far more about your opportunity than the national rate headline alone.
Sellers Should Pay Attention, Too
There is a message here for homeowners considering selling.
With buyer demand more sensitive to affordability, pricing correctly from the beginning becomes increasingly important.
Today's buyers have more information, more choices and tighter monthly-payment constraints.
Homes that are positioned correctly can still attract serious buyers. Properties that start considerably above the market may eventually have to chase buyers through price reductions.
Understanding what buyers are actually purchasing — not simply what nearby homeowners are asking — is increasingly important.
The Bottom Line
Yes, mortgage rates moved back above 7%.
But that is only one part of the September housing market.
National inventory remains higher than last year. Pending sales have slowed. More than four in ten listings have experienced price reductions. And buyers who remain active may have negotiating opportunities that were difficult to find during hotter markets.
The goal should not be to perfectly time mortgage rates.
It should be to understand the complete opportunity in front of you.
If buying makes sense for your finances, lifestyle and long-term plans, today's combination of inventory and negotiating leverage may be worth exploring.
And if the numbers do not work yet?
Knowing that now gives you something much more useful than speculation: a plan.
Ready to Run the Numbers?
Explore your financing options, check your home's value, or see what is currently available across Mid-Missouri.
Jamie Estes
Operating Partner | Estes Group Powered by Place | Keller Williams LO Realty
or another way